Allowance or No Allowance? How Families Decide
Should kids get an allowance? A clear look at the three main approaches (no allowance, a set allowance not tied to chores, and paying for chores), what the CFPB says about how money habits form, how much families typically consider, and how to pick a system that fits your values and budget.
Quick answer: there is no single right answer. Families usually pick one of three systems: no regular allowance, a set allowance that is separate from chores, or pay that is earned for chores or extra jobs. Money educators disagree about tying money to chores, but most agree on two points: children learn money skills by handling real money and making choices with it, and everyday family chores should be expected whether or not money changes hands.
Few parenting questions start as many friendly arguments as allowance. One parent believes kids should never be paid to do their share at home. Another wants children to learn that money comes from work. A third simply wants to stop being asked for a dollar at every checkout.
Each of those goals is reasonable, and each points to a different system. This guide walks through the main options, the arguments behind them and the practical details, such as amount, timing and what the money is for. It sits within our guide to chore charts for kids by age and how to start, which covers the chore side of the decision.
This article is general information for families, not financial advice. Dollar figures quoted below come from the named organizations and authors; they are examples, not recommendations for your budget.
What an Allowance Is Really For
Before choosing a system, it helps to be clear on what you want money to teach. The Consumer Financial Protection Bureau (CFPB) describes three building blocks of financial capability in its youth financial education materials: executive function, financial habits and norms, and financial knowledge and decision-making.
Executive function, such as self-control, planning and working toward a goal, starts developing in early childhood. According to the CFPB, children begin building money habits, norms and values during middle childhood, roughly ages 6 to 12, through a process it calls financial socialization. One milestone the CFPB lists for that age band is feeling confident about age-appropriate money tasks, such as deciding how to spend an allowance and depositing money in a savings account.
That framing matters. An allowance is not only a reward or a payment. It is a practice budget and one of the earliest tools for financial literacy, because children learn the value of money fastest when the money is theirs to manage. A child who has a few dollars a week gets to make small mistakes, such as spending everything on day one, at a cost that is easy to recover from.
Three goals parents usually have
Most families are aiming at one or more of these:
- Money management: learning to budget, save for something and live with a choice.
- Work ethic: connecting effort to earnings.
- Family contribution: helping at home because everyone lives there.
The disagreement between experts mostly comes from which of these goals they put first.
Option 1: No Regular Allowance
Some families never set a weekly amount. Parents buy what children need, and children receive money only as gifts, for birthdays, or for occasional special jobs.
Arguments for
- It keeps money and family chores completely separate.
- There is nothing to track or forget to pay.
- It can suit tight budgets, where a regular payment is hard to keep up.
Arguments against
- Children have few chances to practice choosing between spending and saving.
- Requests for small purchases can turn into daily negotiations.
- Kids may reach their teens without having managed any money of their own.
Families who choose this route can still teach money skills. Letting a child handle birthday money, choose a toy within a set budget, or pay at the store with their own cash covers some of the same ground.
Option 2: A Set Allowance Not Tied to Chores
In this system, children get a regular amount each week or month, and household chores are simply expected as part of family life. Skipping chores leads to a non-money consequence instead of a smaller payment.
This is the approach argued for by Ron Lieber, the former New York Times “Your Money” columnist, in his book *The Opposite of Spoiled*. His view is that an allowance is a teaching tool for spending, saving and giving, while chores are something every family member does. Tying the two together, he argues, risks teaching children that chores are optional if they are willing to give up the money. When chores are skipped, he suggests consequences such as losing screen time or an outing.
Arguments for
- Children get a steady amount to practice budgeting with.
- Chores stay a family responsibility, not a job.
- Parents avoid the “I don’t need the money, so I won’t do it” problem.
Arguments against
- Some parents feel it hands out money without effort.
- It still needs a separate system for chore follow-through.
- The family has to decide what the allowance must now cover, or kids may simply spend it on extras while parents keep buying everything else.
Making it work
Families who use this model often link the allowance to a list of things the child now pays for. A 7 year old might cover small treats and toys. A 12 year old might also cover some entertainment, gifts for friends or part of their clothing budget. The more the allowance covers, the more real the decisions become.
Option 3: Pay for Chores or Extra Jobs
Here, money is earned. The best-known version is the “commission” system promoted by Ramsey Solutions, the personal finance company founded by Dave Ramsey. In an article by Rachel Cruze, the company explains the idea simply: if kids work, they get paid, and if they do not work, they do not get paid. Ramsey Solutions also says that commissioned chores should be separate from routine family chores, which children do because they are part of the family.
Its article gives example rates for young children, such as 25 cents for cleaning up toys or feeding pets and a dollar for helping put groceries away, with larger amounts for older kids’ jobs like mowing the lawn or washing a car. Cruze recommends paying weekly and paying promptly, so children connect the job to the reward.
Arguments for
- It links money directly to effort, which mirrors adult work.
- Children who want more money have a clear way to earn it.
- Extra jobs can lighten the load for parents.
Arguments against
- A child who does not want money that week may decline the work.
- Parents need to track jobs and payments.
- Earnings can swing a lot, which makes budgeting harder to learn.
The common middle ground
Many families end up with a hybrid: daily family chores are unpaid and expected, a small base allowance covers money practice, and bigger extra jobs earn more. That setup tries to keep all three goals in play. The HealthyChildren.org page on chores from the American Academy of Pediatrics also mentions allowances and stickers tied to completed chores as one possible tangible reward, alongside praise, routines and family meetings.
How Much Allowance Is Typical?
No government agency sets an allowance amount, and the right number depends entirely on what the money is meant to cover and what fits your budget. Two rules of thumb come up often:
- About $1 per year of age, per week. Ramsey Solutions says a common rate it sees is up to $1 per week for each year of age for kids up to 12 or 13, and up to $2 per year of age for teens 14 and older, depending on how much they work.
- Match the amount to the expenses you hand over. If you add up what you already spend each month on a child’s treats, small toys and outings, that total can become their allowance, with the child now making the choices.
Ramsey Solutions itself stresses that allowance is personal: the right amount depends on what you consider a fair value for jobs, your budget, your child’s age, what they will buy and whether they will give some away. Starting smaller is easier than cutting back later.
A simple way to set the amount
- List what your child will be expected to pay for.
- Estimate a realistic monthly cost for those items.
- Divide by four or five for a weekly figure.
- Check whether it fits your family budget; if not, shrink the list of covered items.
- Review the amount once a year, ideally on a birthday or at the start of a school year.
If you already track household spending, the free budget printables binder on this site can help you see what a fair figure looks like.
Weekly or Monthly Allowance?
How often you pay changes what children practice. Neither schedule is right for every age, and many families switch as kids grow.
Weekly allowance for younger children
For children under about 9, a week is a long time and a month is almost abstract. A weekly allowance gives them frequent, small chances to make financial decisions and see the results quickly: spend it all on Saturday, and there is nothing left by Wednesday. Ramsey Solutions also recommends paying weekly, and a weekly payday is easier for a young child to remember.
Monthly allowance for tweens and teens
A monthly allowance asks more of a child. They have to stretch one payment over four weeks, which is closer to how adults are paid and budget. It works best once a child can track money on paper or in a banking app and has a list of expenses they now cover, such as entertainment or part of their clothing. Moving from weekly to monthly is a natural step up around the middle school years, often paired with a larger amount.
Delayed gratification and financial goals
Whichever schedule you choose, saving toward something is where an allowance teaches delayed gratification: waiting for a bigger reward instead of spending on a smaller one now. Help your child set financial goals that match their age, such as two weeks for a small toy at 6, or two or three months for a video game at 11. Write the goal down, track progress on a chart or jar, and celebrate when they reach it. Hitting a goal they chose teaches more about money management than any lecture.
Teaching Spend, Save and Give
An allowance teaches more when there is a structure for using it. A common method is three containers, often clear jars, labeled spend, save and give. Lieber’s book describes allowance as a tool for exactly these three uses.
How a three-jar split can work:
- Spend: money the child can use freely within your house rules.
- Save: money set aside for a specific goal, such as a game or a bike, with a picture of the goal taped to the jar.
- Give: money for a cause the child chooses, such as an animal shelter or a school fundraiser.
Some families decide the percentages; others let older children choose. For younger kids, clear jars matter because they can see the money grow. By the tween years, many families move savings into a youth savings account at a bank or credit union so the child can watch a balance and learn about interest.
Opening a kids’ savings account
A kids’ savings account turns the save jar into a real bank account, with statements and, at many banks, a little interest. Accounts for minors are usually opened as a joint or custodial account with a parent or guardian, so ask your bank or credit union what it offers and whether there are fees or minimum balances. Deposits at FDIC-insured banks are protected up to $250,000 per depositor, per bank, per ownership category, and credit unions have similar NCUA coverage. Many families let the child carry the cash to the counter or watch a mobile deposit, so the money still feels real.
Let mistakes happen
The point of practice money is that some choices will be disappointing. A child who spends a week’s allowance on a toy that breaks in a day learns more from that loss than from a lecture. Resist the urge to replace the money. Talk instead about what they might do differently next time.
Talk about money out loud
The CFPB’s youth materials stress that habits and values form through everyday experience. Children learn a lot by hearing how adults compare prices, wait for a sale or decide not to buy something. Narrating those choices at the store costs nothing and backs up whatever allowance system you choose.
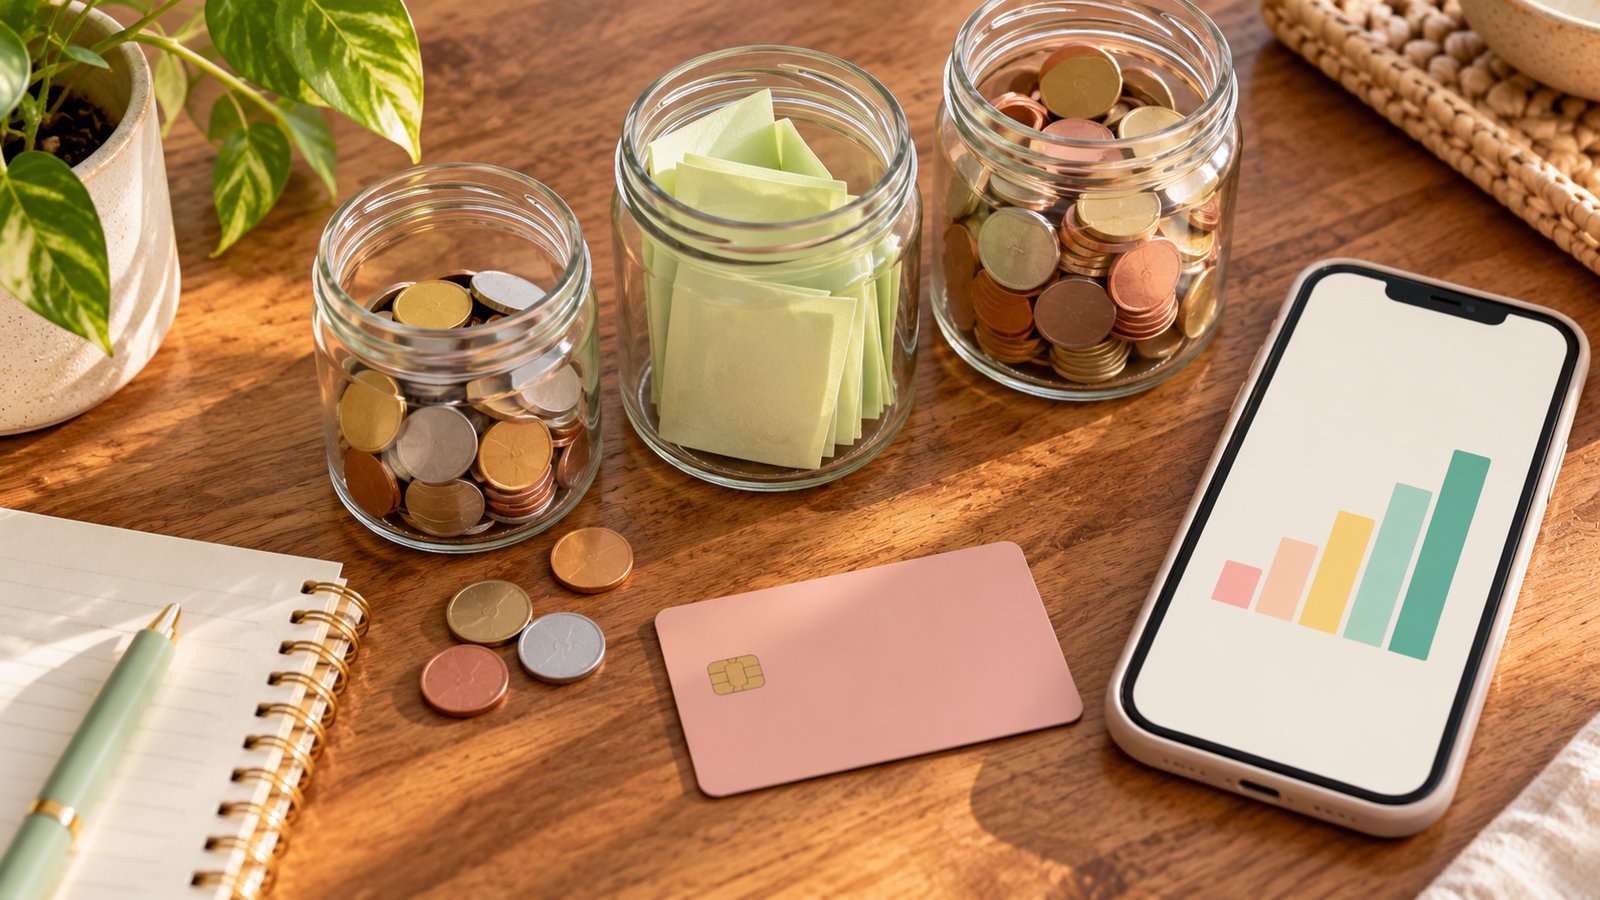
Cash, Jars, Cards or Apps: Choosing a Money System
Once you pick an allowance approach, you still need a budget system for the money itself. The right tool changes with age.
Cash and a piggy bank
For preschoolers and early elementary kids, a cash system works best because coins and bills are concrete. A piggy bank or clear jar lets a child see savings grow, and handing over real money at a store makes the price of a toy feel real in a way a card swipe does not.
Spend, save and give buckets
As kids get older, the three jars become spend, save and give buckets, whether those are envelopes, a written ledger or separate balances in an app. The container matters less than the habit: deciding where money goes before it is spent.
Prepaid debit cards and teen checking accounts
For tweens and teens who shop online or with friends, a prepaid debit card or a teen checking account with a debit card can replace cash. Under the Consumer Financial Protection Bureau’s Prepaid Rule, most prepaid accounts must show a short-form fee disclosure before you buy, so compare monthly, reload and ATM fees. Many banks and credit unions offer youth or teen checking accounts linked to a parent’s account, which gives a child practice with a real balance while you keep oversight. A debit card spends only money already in the account, which makes it a gentler training tool than credit.
Allowance apps
Family banking apps can pay a weekly allowance automatically, track chores and split money into buckets. They can save time, but read the fee schedule and privacy policy, and check whether the money is held in a bank account with deposit insurance through a partner bank.
Allowance and Chores by Age
The right system can change as children grow.
| Age | Common approach | Money skill to practice |
|---|---|---|
| 3 to 5 | No allowance or a very small one; coins in clear jars | Counting, waiting, choosing between two items |
| 6 to 8 | Small weekly allowance or pay for simple extra jobs | Saving for a short-term goal |
| 9 to 12 | Larger allowance that covers some personal expenses, plus optional paid jobs | Budgeting across a month, comparing prices |
| 13 and up | Allowance that covers more expenses, paid jobs, first outside work | Managing a bank account and a debit card |
For the chore side of each age band, see the age-appropriate chores list for ages 2 to 12.
Money Lessons an Allowance Can Teach
An allowance is a small amount of money, but it can carry big life lessons. These are the ideas families most often try to teach with it, and simple ways to show each one.
Opportunity cost
Every choice to spend is also a choice not to buy something else. When a child picks a slime kit over a book, name the opportunity cost out loud: “If you buy this, you won’t have money for the book this week.” Over time, children start doing that math themselves before they buy.
Buyer’s remorse and responsible spending
Most kids eventually spend on something that disappoints them. That feeling of buyer’s remorse is useful. Ask what they would do differently, and suggest a waiting rule, such as sleeping on any purchase over a set amount. Responsible spending is less about never buying treats and more about matching purchases to what the child actually values.
Needs vs discretionary spending
Explain that adults divide money into needs, such as housing, food and utilities, and discretionary spending, the money left for wants. A child’s allowance is mostly discretionary money, which is exactly why it is a safe place to practice making financial decisions.
Compound interest
Savings grow faster when interest earns interest. A simple example: $100 left in an account earning 5 percent a year, compounded annually, grows to about $163 after 10 years with no new deposits. Real rates vary and are often lower on kids’ accounts, but even a little interest shows a child that money left alone can grow. Older kids can try the free compound interest calculator on Investor.gov, a site run by the U.S. Securities and Exchange Commission.
Credit-card debt and other financial pitfalls
Teenagers will soon face financial pitfalls such as overdraft fees, buy-now-pay-later plans and credit-card debt. The Credit CARD Act of 2009 generally requires credit card applicants under 21 to show independent income or have a cosigner, so many young adults get their first card in college or soon after. Explaining how interest on an unpaid balance grows, the reverse of compound interest in a savings account, prepares them before the first offer arrives.
Cost of living and financial independence
For teens, connect the allowance to the real cost of living. Look together at what rent, groceries, a phone plan or car insurance cost where you live. That conversation turns the abstract goal of financial independence into numbers they can plan for, and it makes the link between hard work, steady income and choices easier to see.
Teaching responsibility, not just math
The deeper lesson is teaching responsibility. A child who manages a childhood allowance, keeps up with tasks and chores and lives with their own choices is building financial skills and personal habits together. Those financial management habits carry straight into handling personal finances as an adult.
How to Choose a System for Your Family
There is no wrong choice among the three options as long as it is consistent and matches your goals. A few questions help you decide:
- What is your top goal? If it is money management, a set allowance gives the most practice. If it is work ethic, paid extra jobs fit better. If it is keeping chores and money separate, a non-chore allowance or no allowance works.
- What can you sustain? A system that pays weekly only works if you pay weekly. Forgotten payments teach children that promises about money are soft.
- What will the money cover? Write this down and share it with your child.
- What happens when chores are skipped? Decide in advance, whether it is a lost privilege or lost pay.
- How will siblings be treated? Age-based amounts usually feel fair to children; identical amounts at different ages often do not.
Talking the system through with your child at a calm moment, or at a weekly family meeting, makes it much more likely to stick. Write the rules on the family chore chart, so both the chore system and the money system are clear and no one has to rely on memory.
Signs it is time to adjust
- Your child runs out of money every week and asks for advances.
- Chores have turned into constant negotiation about pay.
- The allowance no longer covers what it was meant to.
- An older child has a part-time job and needs a different arrangement.
Any of these is a reason to revisit the system, not to scrap it.
Building toward bigger life skills
Whatever system you choose, the bigger aim is a young adult who can budget, save and earn. Allowance is one tool among many on the path to the life skills kids must know, alongside cooking, cleaning and basic first aid. For help with the chore half of the equation, these tips on getting kids to do chores pair well with any money system.
Frequently Asked Questions
At what age should kids start getting an allowance?
There is no official starting age. A practical signal is when a child can count coins and understand waiting to buy something. The CFPB places the development of money habits mainly in middle childhood, roughly ages 6 to 12.
What is the difference between a weekly and monthly allowance?
A weekly allowance gives younger children frequent, small chances to practice. A monthly allowance asks older kids to budget one payment across four weeks, which is closer to adult money management. Many families switch from weekly to monthly in the tween years.
Should my child have a bank account?
A kids’ savings account is a helpful next step once a child is saving toward goals regularly. Minors usually need a parent or guardian on the account, so compare joint and custodial options, fees and interest at your bank or credit union.
Should allowance be tied to chores?
Experts disagree. Ron Lieber argues it should not be, so chores stay a family responsibility. Ramsey Solutions recommends paying a commission for work, while keeping basic family chores unpaid. Many families combine the two.
How much allowance should a 10 year old get?
There is no official figure. One rule of thumb cited by Ramsey Solutions is up to $1 per week per year of age, so up to about $10 a week, but the right amount depends on what the money must cover and your budget.
What should kids spend their allowance on?
Agree on a list in advance. Younger children often cover small treats and toys; older children may add entertainment, gifts and part of their clothing budget.
What if my child spends all their allowance at once?
Let it happen and avoid refilling the money. Use the moment to talk about planning, then try a spend, save and give split for the next payment.
Is it okay to not give an allowance?
Yes. Children can still practice money skills with gift money, a set shopping budget or paid one-off jobs.
Should kids have a debit card?
Many families add a prepaid debit card or a teen checking account with a debit card in the tween or teen years, once a child is shopping on their own. Compare fees first, and keep the account linked to a parent so you can help with mistakes.
How do I explain compound interest to a child?
Use a simple example: $100 earning 5 percent a year, compounded annually, grows to about $163 in 10 years because interest earns interest. A calculator such as the one on Investor.gov lets older kids try their own numbers.
Sources
- Consumer Financial Protection Bureau, Financial habits and norms and related youth financial education building blocks.
- Ron Lieber, *The Opposite of Spoiled: Raising Kids Who Are Grounded, Generous, and Smart About Money* (HarperCollins, 2015).
- Ramsey Solutions, Rachel Cruze, Should Kids Get an Allowance? (updated February 2025).
- American Academy of Pediatrics, HealthyChildren.org, Age-Appropriate Chores for Children.
- Federal Deposit Insurance Corporation, Deposit Insurance ($250,000 per depositor, per insured bank, for each account ownership category); National Credit Union Administration share insurance.
- Consumer Financial Protection Bureau, Prepaid Accounts Rule (short-form fee disclosure).
- U.S. Securities and Exchange Commission, Investor.gov compound interest calculator.
- Credit Card Accountability Responsibility and Disclosure (CARD) Act of 2009 (applicants under 21).